Insurance at checkout, in the banking app, in the car configurator: Embedded insurance is seen as a growth opportunity for the industry. A white paper by the Dutch InsurTech company MavenBlue takes a look behind the scenes. That’s where it will be determined whether success remains manageable.
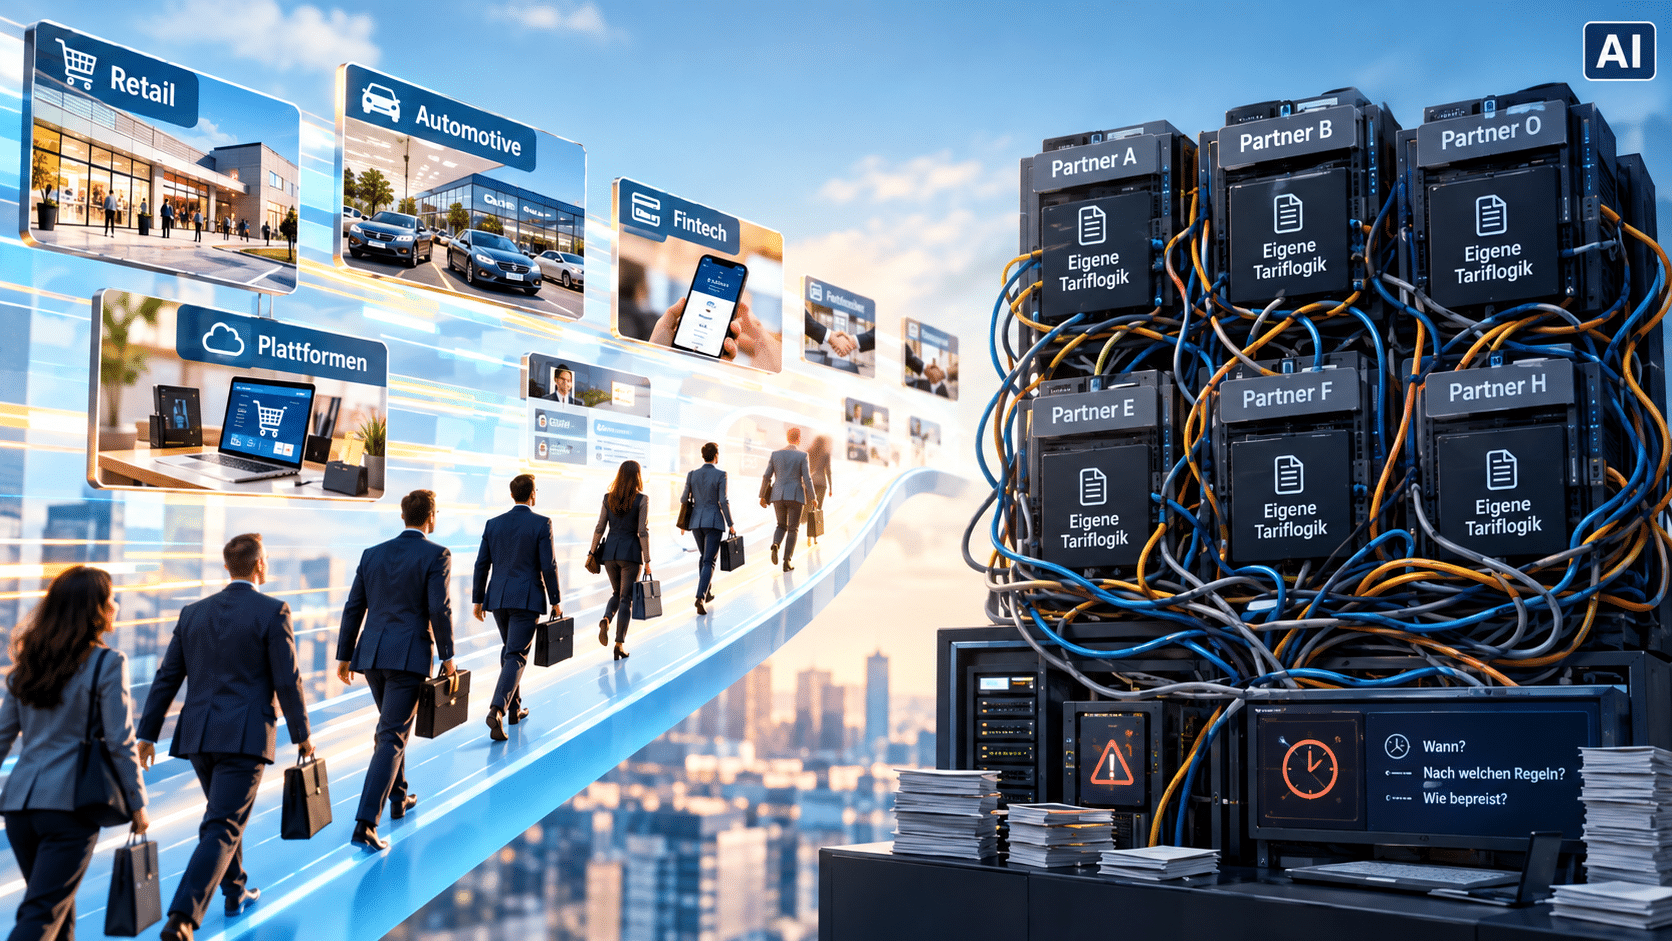
The idea isn’t new, bancassurance and affinity programs have been around for decades. What is new is the pace and scale at which insurers are partnering with retailers, automakers, fintech companies, and platforms. MavenBlue notes that there is strikingly little discussion of the operational side of this. The problem rarely lies in the business model, but rather in the architecture: Each new partner is treated as a one-off, with its own integration, its own copy of the pricing logic, and its own record of what was priced when and according to which rules. The offering scales, but the infrastructure behind it does not.
Ten integrations, ten truths
For IT, this means technical debt that grows quietly. According to the paper, ten integrations built this way aren’t ten times the effort of one, they’re ten places where the same logic can drift apart. A pricing adjustment becomes a program with its own release schedule for each partner, and the tenth partner tends to get off to a slower start than the first.
For actuaries, the number of variations multiplies: one risk, dozens of nearly identical rate structures. The pitfall lies in seemingly minor details, such as a rounding rule or a minimum premium. Determining the rate basis on which a specific quote was generated on a specific day can then only be answered by tracing the details.
What the board of directors doesn’t see
The board of directors and risk functions are liable for every product sold under the company’s license, no matter how invisible the insurer is within the distribution channel. The white paper identifies three sensitive areas: fair value, which European regulators scrutinize closely in the case of embedded supplementary coverage, model governance in light of the EU AI Act, and concentration risk. A partner portfolio that has grown organically can easily obscure just how much exposure is concentrated among a few large partners—until it becomes significant.
Build it once, configure it in many ways
The answer follows from the diagnosis. Rate and underwriting logic belong in a central layer with a single version history, to which partners connect via a unified interface. Price points, limits, commissions, and branding are configured rather than reprogrammed, and the audit trail is created automatically. This should reduce onboarding time from weeks to months to just days to weeks. What MavenBlue does not promise is this: the actuarial work on risks with limited data remains, and those who connect only a handful of partners may have to make do with custom solutions.
The questions remain human
It’s no surprise that a pricing software provider would focus on the pricing layer. The paper avoids mentioning product names, but it also omits figures and case studies. The most valuable part is the list of questions at the end: How many systems would we have to modify if a pricing factor changed today? Would we notice a concentration before it becomes significant? A clean architecture provides insight into these questions. Ultimately, someone with sound judgment must still be held accountable.
Binci Heeb
See also: Four new insurtech companies, a software giant, and an award with five trophies
Search:
Sponsors: